Insurance claims automation applies AI, intelligent document processing, and workflow orchestration to move a claim from first notice of loss to settlement with minimal manual handling. Done well, it cuts cycle time, reduces cost per claim, and improves customer satisfaction without gutting the human judgment regulated claims still require. The right next step isn’t a full platform overhaul. Pick one high-volume, low-complexity claim stream, like windshield or minor auto damage, and pilot automation there first.
TL;DR:
- Automating high-volume, low-complexity claims such as windshield or minor auto damage can significantly increase straight-through processing rates and reduce cycle times.
- Starting with simple claim types allows for gathering trustworthy evidence and building confidence before expanding automation to more complex, high-risk claims.
- A phased approach, including shadow testing and incremental threshold increases, minimizes risk and helps adjust automation confidence conservatively at launch.
- Using a combination of IDP, ML classification, and API connectors enables scalable and compliant automation while maintaining control over sensitive data.
- Successful implementation hinges on governance, staff buy-in, and clear escalation paths to ensure automation complements human judgment and maintains regulatory standards.
Table of Contents
- What Claims Automation Actually Covers
- How Automated Claims Processing Works Step by Step
- The Technology Stack Behind Automated Claims
- Metrics That Prove Claims Automation Is Working
- A Phased Roadmap for Rolling Out Claims Automation
- Governance, Audit Trails, and Compliance Controls
- What Realistic Automation Outcomes Look Like
- Why the Build Decision Matters as Much as the Technology
- Getting Adjusters and Staff to Trust the New Workflow
- How Automation Changes the Customer Experience
- What Insurers Consistently Get Wrong About This
- Build Your Claims Automation With a Partner, Not a Vendor
- Sources
- FAQ
What Claims Automation Actually Covers
Claims automation isn’t one tool. It’s a set of automated handoffs across five stages: first notice of loss (FNOL), intake, triage, adjudication, and settlement. Each stage can run fully automated, partially automated, or stay entirely manual, depending on complexity and risk.
Full straight-through processing (STP) means a claim moves from intake to payout with zero human touch. That’s the ceiling, not the floor. According to InsurerBrain’s definition of STP, many insurers still route the majority of claims to human adjusters, reserving full automation for the simplest, most predictable cases. A hybrid, human-in-the-loop model is the realistic operating mode for most carriers, not a stopgap.
Where should you start looking for automation candidates?
- FNOL intake: high volume, low judgment required, ideal for chatbots and mobile capture
- Document triage: sorting police reports, photos, and repair estimates by type and urgency
- Adjudication for low-severity claims: auto glass, minor property damage, small liability payouts
- Settlement processing: templated payout letters, e-signature routing, payment issuance
- Post-settlement tasks: subrogation referrals, customer surveys, closure notices
Complex claims, catastrophe losses, and anything with fraud indicators or coverage disputes should stay human-led, at least for final sign-off. Automation there means faster document prep and triage, not autonomous decisions.
How Automated Claims Processing Works Step by Step
The mechanics follow a predictable sequence, even though every carrier’s stack looks a little different underneath it.
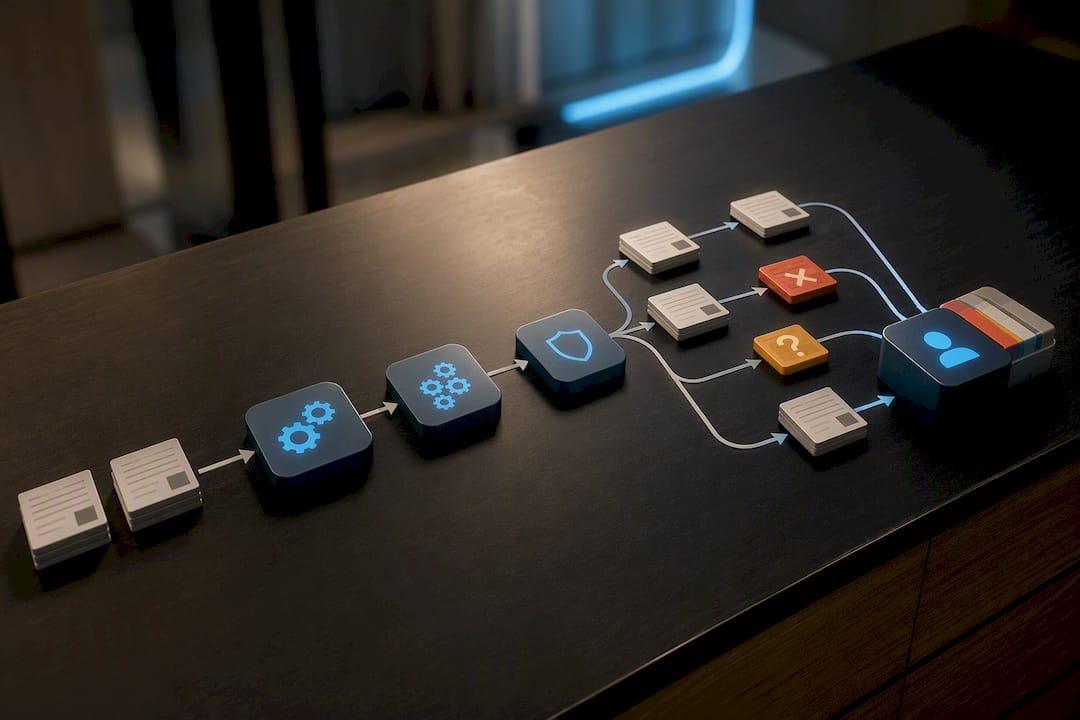
- Multi-channel FNOL intake. Claims arrive through a mobile app, a web form, a phone call transcribed by speech-to-text, or an API feed from a partner. The system matches the claim to an existing policy record and opens a case file automatically.
- Document extraction and normalization. Intelligent document processing (IDP) pulls structured data out of PDFs, photos, and handwritten forms. Field mapping normalizes vehicle identification numbers, dates, and dollar amounts so downstream systems can read them consistently.
- Triage and severity scoring. A model scores each claim for complexity and estimated payout, then routes it to a queue with an appropriate SLA. Simple claims go to a fast lane; anything scoring high on severity or fraud risk gets flagged for a human adjuster.
- Decision engine adjudication. Rules-based or ML-assisted decision engines check policy terms, coverage limits, and deductibles, then either approve, deny, or escalate. Exceptions, anything outside pre-set confidence thresholds, route automatically to a human queue rather than forcing a bad automated call.
- Settlement and payment orchestration. Approved claims generate templated settlement letters, route for e-signature where needed, and trigger payment through integrated payment rails. The system logs every step for audit purposes as it goes.
Pro Tip: Set your automation confidence threshold conservatively at launch, even if it means routing more claims to humans than the model technically supports. You can lower the threshold as you accumulate evidence the model performs consistently across claim types, but starting too aggressive erodes adjuster trust fast.
The exception path matters as much as the happy path. A claim that fails extraction, scores ambiguously on severity, or trips a fraud flag needs a clean handoff to a human adjuster with full context, not a dead end that forces the customer to start over.
The Technology Stack Behind Automated Claims
Four technology categories do the heavy lifting, and each comes with real trade-offs worth weighing before you commit budget.
Intelligent document processing (IDP) extracts and structures data from unstructured sources: scanned forms, repair estimates, medical records. Document-heavy workflows remain the primary obstacle to higher STP rates, since unstructured and handwritten content still requires more advanced IDP capability than most legacy OCR tools deliver. Accuracy on typed forms tends to be strong; handwriting and low-quality photos still need human review loops.
Machine learning models handle classification (what type of claim is this), named-entity recognition (pulling names, dates, and amounts out of free text), and severity scoring. These need ongoing governance: monitoring for drift, documented validation, and a clear owner when performance degrades.
RPA versus API-first connectors is a real architectural choice. Robotic process automation (RPA) mimics human clicks through legacy screens, useful for bolting automation onto core systems that lack modern APIs. API-first integration is more stable and faster to maintain, but only works when the underlying system exposes the right endpoints. Most carriers end up running both, RPA for the oldest systems, APIs everywhere else.
Decision engines encode policy rules and payout logic so adjudication doesn’t require a human to re-check coverage terms on every claim. Combining IDP with workflow automation and decision logic can meaningfully raise straight-through rates and cut cycle times, though full automation remains the exception rather than the rule across the industry.
Deployment model matters more in insurance than most industries. Self-hosted or private cloud deployment keeps claimant data, medical records, and policy details inside your own security perimeter, a meaningful consideration given how much regulated personal data flows through a single claim file.
Metrics That Prove Claims Automation Is Working
You need a baseline before you can claim any improvement. Measure current cycle time, cost per claim, and error rates for at least one full quarter before automating anything.
Track these five metrics from day one of the pilot:
- Cycle time: days from FNOL to settlement, broken out by claim complexity tier
- STP rate: percentage of claims resolved with zero human touch, by line of business
- Cost per claim: fully loaded, including adjuster time, technology cost, and payout processing
- Accuracy and quality: rate of overturned decisions, reopened claims, and adjuster overrides
- Customer satisfaction (NPS or CSAT): measured specifically on the claims experience, not overall brand sentiment
A minority of claims achieve complete straight-through processing industry-wide, so set improvement targets against your own baseline rather than a vendor’s marketing number. A jump from 15% to 35% STP on your simplest claim tier is a real win, even if it’s nowhere near “full automation.”
Report these metrics monthly during the pilot, then quarterly once the program stabilizes, with guardrail alerts (a spike in overturned decisions, for instance) reviewed weekly regardless of cadence.
A Phased Roadmap for Rolling Out Claims Automation
Rushing straight to full deployment is the single most common failure mode. A phased rollout limits blast radius and builds internal confidence with evidence instead of promises.
- Discovery (4 to 6 weeks). Map current claim volumes by type, complexity, and cycle time. Identify the one or two claim streams with the highest volume and lowest judgment complexity, your pilot candidates.
- Data preparation. IDP and ML models need representative training data. Pull a sample across at least several hundred historical claims per document type to validate extraction accuracy before going live.
- Pilot in shadow mode. Run the automated workflow in parallel with your existing human process, without acting on its output, to compare decisions before anyone trusts it with real payouts.
- Progressive STP thresholds. Once shadow-mode accuracy holds steady, start letting the system act autonomously on the highest-confidence claim segment only, then expand the threshold gradually.
- Scale and integrate. Extend to additional claim types, connect to adjacent systems (SIU, subrogation, finance), and formalize new SLAs around the automated workflow.
Pro Tip: Keep your core policy administration system as the system of record throughout the rollout. Layer the automation on top rather than replacing core infrastructure, it’s far less risky and lets you roll back a stage without touching the underlying data.
Integration with legacy core systems is usually the slowest part of this timeline, not the AI itself. Budget real time for it. Operationally, this phase also means retraining adjusters on exception handling instead of routine processing, redefining SLAs around new cycle-time expectations, and testing with A/B splits before committing to full rollout on any given claim segment.
Governance, Audit Trails, and Compliance Controls
Automated decisions in insurance need to be defensible, not just fast. That starts with immutable logs capturing not just what decision was made, but the rationale behind it, which fields the model weighted, what confidence score triggered approval, and what rule fired if it was rules-based.
Build these controls in before scaling past the pilot:
- Decision rationale capture: every automated decision logs its inputs, confidence score, and triggering rule or model output
- Model validation and drift monitoring: scheduled reviews checking whether model accuracy is degrading against fresh claim data
- Fraud flagging at intake: automated triggers that route suspicious claims to a Special Investigation Unit (SIU) rather than letting them proceed on autopilot, especially important given how much insurance fraud costs the industry according to FBI analysis
- Data sovereignty controls: clear documentation of where claimant data lives and who can access it, particularly under self-hosted or private deployment models
- SLA and fairness guardrails: escalation paths that guarantee a claimant unhappy with an automated decision reaches a human reviewer within a defined window
Regulators increasingly expect insurers to explain automated decisions on demand, not reconstruct them after the fact. Design your audit trail for that standard from the start.
What Realistic Automation Outcomes Look Like
Vendor pitches often promise near-total automation within months. Real deployments look more modest, and more durable.
A typical pilot on low-value auto claims starts with a baseline cycle time of several days and an STP rate in the low double digits. After a few months of shadow mode and progressive threshold expansion, carriers commonly see STP roughly double or triple on that specific claim segment, with cycle time cut by half or more, before expanding to additional lines of business. Scaling beyond the pilot segment typically takes another two to three quarters, not weeks.
Catastrophe (CAT) events test the model differently. Claim volume spikes fast, so automation needs configurable assignment rules and temporary authority changes, letting adjusters approve larger payouts than usual, that can activate and then wind back down without a manual system reconfiguration each time.
The gap between marketing claims and reality:
- Claim: “Full automation of your claims process”; Reality: hybrid automation on your simplest claim tiers, human oversight everywhere else
- Claim: “Deploy in weeks”; Reality: discovery and data prep alone often take four to six weeks before pilot launch
- Claim: “Eliminate manual review”; Reality: exception routing to humans is a permanent, necessary feature, not a bug to engineer away
Why the Build Decision Matters as Much as the Technology
Most of the failure modes in claims automation trace back to a build decision made too early, not a technology limitation. Off-the-shelf platforms move fast but lock you into someone else’s data model, someone else’s roadmap, and often someone else’s servers holding claimant records you’re legally responsible for.
Some vendors work with insurers and other regulated firms on a different premise: co-build the system with your team rather than license a black box. That means your domain experts, the adjusters and claims directors who actually know where the exceptions live, shape the workflow logic directly instead of filing feature requests into a vendor backlog. Deployment options that keep data under the client’s own control matter here, since claimant records, medical details, and policy data are exactly the kind of information regulated insurers can’t afford to hand off to a third-party server without clear governance answers.
The decision criteria are straightforward: if your claim types are standard and your compliance requirements are light, an off-the-shelf tool may serve you fine. If your workflows are specific to your book of business, or your regulatory obligations demand tighter control over where data lives and how decisions get documented, a co-built system is the more defensible long-term choice.
Getting Adjusters and Staff to Trust the New Workflow
Automation projects fail more often from adjuster resistance than from bad models. Adjusters who’ve spent years developing judgment on claim severity understandably distrust a system that starts making some of those calls for them.
Start change management before the pilot launches, not after. Involve senior adjusters in defining the exception rules, the specific triggers that should route a claim to a human rather than let it process automatically. When adjusters help write the rules, they trust the system that enforces them.
Training needs to shift too. Instead of training adjusters to process routine claims faster, train them to handle the exception queue, the harder, more ambiguous cases that automation surfaces once it’s absorbed the routine volume. That’s a different skill set: faster judgment on complex claims, not faster paperwork on simple ones.
Communicate the “why” clearly and repeatedly. Staff who understand that automation is absorbing the repetitive work, not replacing their jobs, adapt faster than staff who hear about the rollout secondhand. Publish early pilot metrics internally, including the exception rate, so adjusters see the system is routing hard calls to them, not hiding them.
Expect a dip in productivity during the transition as staff learn new queues and tools. Budget for it in your rollout timeline rather than treating it as a failure signal.
How Automation Changes the Customer Experience
Claimants notice speed before they notice anything else about a claims process. A claim that settles in two days instead of two weeks changes how a customer feels about the entire policy relationship, not just that one claim.
Automated communication does most of the heavy lifting here. Status update triggers, sent automatically at each stage transition, replace the “check back in a few days” black hole that frustrates most claimants. A claimant who gets a text the moment their photos clear IDP extraction feels informed even before a decision is made.
The risk runs the other direction too: automation that removes a human contact point entirely, with no clear escalation path, damages trust fast when something goes wrong. Build a visible, easy escalation option into every automated communication, a reply option, a callback request, something that reaches a person within a defined SLA window.
Settlement automation should extend the same clarity. Templated payout letters that explain the calculation, not just the number, reduce disputed claims and repeat contact volume. E-signature and instant payment orchestration close the loop fast enough that customers experience automation as a benefit rather than a black box that happened to them.
What Insurers Consistently Get Wrong About This
Most claims automation advice treats the technology choice as the hard part. It isn’t. The hard part is deciding what to automate, in what order, with what evidence of readiness, and that’s a sequencing and governance problem more than an engineering one.
The conventional wisdom pushes carriers toward the biggest, highest-impact claim segment first, on the theory that bigger wins justify bigger budgets. That’s backwards. The highest-value early target is the most predictable claim segment, even if it’s a small one, because the goal of a first pilot is generating trustworthy evidence, not maximizing dollar impact. You earn the right to automate complex claims by proving the model out on simple ones first.
The other overrated idea is that off-the-shelf platforms are inherently faster to deploy than a co-built system. They’re faster to switch on, not necessarily faster to value, especially once you factor in the customization work most carriers end up doing anyway to fit their specific policy language and claim types. A system built around your actual workflow from the start often reaches useful STP rates faster than a generic platform retrofitted to match it.
— Matevz
Build Your Claims Automation With a Partner, Not a Vendor
Some firms build AI-native claims systems with insurers directly, instead of licensing a fixed platform you have to bend your workflow around. Adjusters and claims directors shape the automation logic from the start, and deployment options that keep client data under the client’s own control matter for exactly the kind of claimant records this article has walked through: medical details, policy terms, and payout history that regulated insurers can’t hand off without clear answers on where it lives and who can see it.
That control comes with a real trade-off worth naming: a co-built system takes longer to reach first deployment than flipping on a subscription tool, because it’s built around your actual claim types and exception rules instead of a generic template. What you get in exchange is a system your team owns outright, with a workflow that already fits your book of business instead of one you’ll spend the next year customizing to fit it. If your claims volume, compliance obligations, or claim complexity make an off-the-shelf platform feel like a compromise, start with a pilot scoping conversation at Autonomousfirm or review the co-build model at Benchmarked to see how a scoped assessment works.
Sources
The FBI’s insurance fraud analysis covers the scale of fraud risk automated systems need to flag. Financial Times coverage frames industry-wide AI adoption trends. InsurerBrain’s STP definition clarifies the technical baseline this article builds on.
- Insurance Fraud — FBI
FAQ
What Is Claims Automation?
Claims automation uses AI, intelligent document processing, and workflow orchestration to move claims through first notice of loss, triage, adjudication, and settlement with reduced manual handling, ranging from partial automation to full straight-through processing.
What Is Automation in Insurance More Broadly?
Beyond claims, insurance automation covers underwriting, policy servicing, and billing, but claims automation typically delivers the fastest measurable ROI because claim workflows are repetitive, document-heavy, and time-sensitive.
Are Insurance Companies Actually Using AI for Claims?
Yes. Financial Times reporting on the sector’s technology investment confirms AI-driven claims processes are a major focus of industry adoption, though most carriers run hybrid models rather than full automation.
Which Technologies Automate Recovery Steps Like Subrogation in Claims?
Post-settlement recovery tasks typically use decision engines to flag subrogation-eligible claims automatically, combined with RPA or API connectors to route referrals to recovery teams or third-party subrogation partners without manual case review.
Is a Custom-Built Claims Automation System Better Than an Off-the-Shelf Platform?
It depends on your claim complexity and compliance needs. A co-built system, the model Autonomousfirm uses, fits your specific workflow and keeps data under your own control, while off-the-shelf tools deploy faster for standard, low-complexity claim types.